



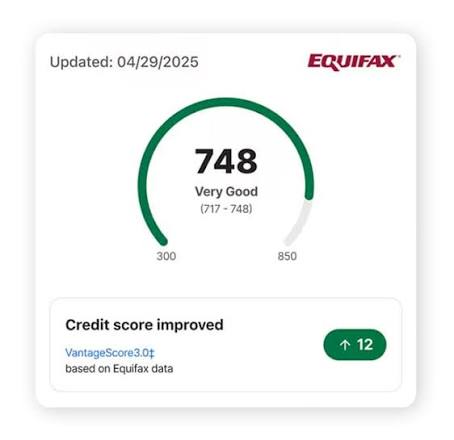
Hire Credit Score Hacker To Fix Credit Score
$200.00
Hire Credit Score Hacker To Fix Credit Score
Tired of improving your credit score. Our credit management team provides you with permanent solutions that keep you waiting endlessly for your credit repair. We have expertise in Experian, TransUnion and Equifax credit report revisions. Get your credit score hack now!
Hire Credit Score Hacker to Fix Credit Score: What You Need to Know
If you have a low credit score, you may come across services advertising themselves as a “credit score hacker” or claiming they can quickly hack, manipulate, or erase negative information from a credit report.
Be careful with these offers. There is no legitimate way to simply hack a credit bureau and change an accurate credit history. A reputable credit repair professional, financial counselor, or credit specialist can instead help you identify legitimate errors, understand your credit report, dispute inaccurate information, and develop a strategy for improving your credit over time.
The Federal Trade Commission warns that companies cannot legally remove accurate and current negative information from a credit report. Promises to do so are a major warning sign of a credit-repair scam.
What Does “Credit Score Hacker” Mean?
The phrase credit score hacker is often used online to describe someone who claims they can manipulate a person’s credit profile.
In reality, a legitimate professional should not attempt to gain unauthorized access to credit bureau systems or alter records illegally.
Instead, legitimate credit assistance may involve:
- Reviewing your credit reports
- Identifying inaccurate information
- Disputing legitimate reporting errors
- Investigating identity-theft-related accounts
- Understanding outstanding debts
- Developing a debt repayment strategy
- Improving payment history
- Reducing credit utilization
- Monitoring your credit reports
- Providing financial education
These are very different from illegally hacking a credit bureau.
Can Someone Hack Your Credit Score?
Your credit score is calculated using information contained in your credit history. There is no legitimate shortcut that allows someone to simply hack the system and replace a poor score with an excellent one.
If your credit report contains inaccurate or incomplete information, you have the right to dispute it. The FTC explains that consumers can dispute errors with both the credit bureau and the business that supplied the information.
If the information is accurate, however, a credit repair company cannot legally make it disappear simply because it negatively affects your score.
Hire a Credit Repair Expert Instead
If you need help improving your credit, consider looking for a legitimate credit repair specialist or nonprofit credit counselor rather than someone advertising illegal hacking services.
A qualified professional can help you understand:
- What is hurting your credit
- Which accounts may contain errors
- How to dispute inaccurate information
- How payment history affects your profile
- How outstanding balances affect credit utilization
- Which debts should be prioritized
- How to build better financial habits
The right strategy depends on your individual credit history.
How to Fix Errors on Your Credit Report
One of the most important legitimate ways to improve your credit profile is to correct information that is inaccurate.
Start by reviewing your credit reports carefully.
Look for:
- Accounts you do not recognize
- Incorrect payment histories
- Incorrect account balances
- Duplicate accounts
- Wrong personal information
- Incorrect dates
- Accounts that should no longer be reported
- Identity-theft-related accounts
If you identify an error, gather documentation supporting your claim.
The FTC recommends contacting the credit bureau and the company that provided the inaccurate information. The dispute should clearly identify the information you believe is incorrect and include supporting documentation.
What Happens After a Credit Dispute?
When you dispute inaccurate information, the credit bureau generally investigates the claim and contacts the company that supplied the information.
The FTC says credit bureaus generally have 30 days to investigate a dispute, although certain circumstances can affect the process.
If the information is determined to be inaccurate, it should be corrected.
Keep copies of your dispute letters, supporting documents, responses, and other relevant records.
What If the Negative Information Is Accurate?
This is where legitimate credit repair differs from a supposed “credit score hacker.”
If a late payment, collection account, or other negative item is accurate and current, you generally cannot simply dispute it by claiming it is inaccurate.
The FTC states that accurate negative information cannot legally be removed merely because it hurts your credit.
Instead, improving your credit usually requires time and consistent financial behavior.
That can include paying bills on time, reducing debt, and avoiding unnecessary new credit obligations.
Be Careful With Credit Repair Guarantees
One of the biggest warning signs is a company promising a specific dramatic increase in your credit score.
For example, be cautious if someone claims:
- “We can raise your score by 200 points guaranteed.”
- “We can erase every negative account.”
- “We can delete accurate collections.”
- “We can remove your bankruptcy.”
- “We can create a new credit identity.”
- “We can hack the credit bureau.”
- “We can fix your credit in a few days.”
These claims should be treated with extreme caution.
The FTC has repeatedly warned consumers about credit-repair operations that promise easy fixes or claim they can remove accurate negative information.
Never Create a False Credit Identity
Some fraudulent services may promise to create a “new credit identity” so that consumers can avoid their existing credit history.
Do not follow these instructions.
The FTC specifically warns against schemes involving false identity information, fake identity-theft claims, or attempts to hide legitimate credit histories
A legitimate credit professional should help you correct genuine errors and improve your financial position—not create false information.
Be the first to review “Hire Credit Score Hacker To Fix Credit Score”
Related products
Black Hat Hacker
Black Hat Hacker
Black Hat Hacker
Black Hat Hacker
Black Hat Hacker
Black Hat Hacker
Black Hat Hacker
Black Hat Hacker
Reviews
There are no reviews yet.